How do banks profit, and where does their revenue come from?
Banks, often perceived as monolithic institutions, generate revenue through a complex web of activities that go far beyond simply holding your money. Understanding these revenue streams is crucial for grasping the entire financial ecosystem and making informed decisions about your own finances. Their profitability stems from a fundamental principle: they borrow money at a lower cost than they lend it out, capturing the spread as profit. This core function underpins a vast array of services and activities.
One of the most significant contributors to bank revenue is interest income. This arises primarily from loans extended to individuals and businesses. Mortgages, car loans, personal loans, and business loans all generate interest payments that flow directly into the bank's coffers. The difference between the interest rate the bank charges on these loans and the interest rate it pays on deposits (savings accounts, certificates of deposit, etc.) is known as the net interest margin (NIM). A wider NIM translates to higher profitability. Banks actively manage their loan portfolios, assessing risk and adjusting interest rates accordingly to maximize their NIM while remaining competitive. They employ sophisticated credit scoring models and underwriting processes to mitigate the risk of loan defaults, ensuring a steady stream of interest income. Furthermore, banks engage in securitization, packaging loans into marketable securities and selling them to investors. This allows them to free up capital for further lending and generate additional revenue through fees associated with the securitization process. The volume and type of loans a bank originates significantly impact its overall interest income. Banks focusing on higher-risk loans, like subprime mortgages, may generate higher interest income, but also face a greater risk of default, as seen during the 2008 financial crisis.
Beyond lending, banks derive significant revenue from fees and commissions. These fees are charged for a wide range of services, including account maintenance, overdraft protection, ATM usage, wire transfers, and safety deposit boxes. While individually these fees might seem small, they accumulate into a substantial revenue stream, particularly for larger banks with millions of customers. Investment banking divisions within larger banks generate substantial income through fees earned from advising companies on mergers and acquisitions (M&A), underwriting initial public offerings (IPOs), and managing bond issuances. These services are highly specialized and require significant expertise, justifying the high fees charged. Banks also offer wealth management services, providing financial planning, investment advice, and portfolio management to high-net-worth individuals and institutions. These services typically generate revenue through management fees (a percentage of assets under management) and performance fees (a percentage of profits generated). Brokerage services, where banks facilitate the buying and selling of securities for clients, also contribute to fee income. The shift towards online banking and automated services has, in some cases, reduced the reliance on certain fees (e.g., branch transactions), but has also created new fee opportunities (e.g., premium online banking services).
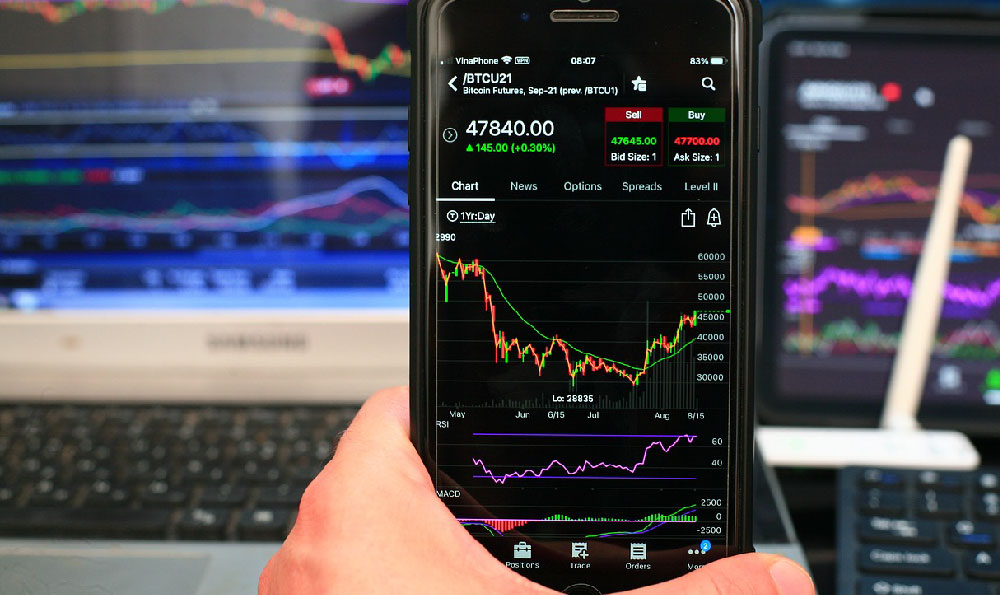
Trading activities represent another important source of revenue, especially for larger investment banks. Banks engage in trading securities, currencies, and commodities on their own account (proprietary trading) or on behalf of clients. They profit from the price fluctuations in these markets, using sophisticated trading strategies and risk management techniques. Market making, where banks provide liquidity by buying and selling securities to facilitate trading, is another key activity that generates revenue through the spread between the bid and ask prices. However, trading activities are inherently risky and can lead to significant losses if not managed effectively. Regulations such as the Dodd-Frank Act have placed restrictions on proprietary trading to limit the risks banks can take with depositors' money. The revenue generated from trading is highly volatile and depends on market conditions and the bank's trading expertise.
Another significant, though often overlooked, revenue stream comes from investment management and asset management activities. Banks manage vast portfolios of assets, including stocks, bonds, real estate, and alternative investments, on behalf of institutional clients such as pension funds, insurance companies, and sovereign wealth funds. They generate revenue through management fees, performance fees, and other related charges. The scale of these assets under management can be enormous, making investment management a crucial profit center for many large banks. The performance of these managed assets directly impacts the bank's revenue, making expertise in asset allocation and investment strategy essential.
Furthermore, banks profit from providing custodial services, safeguarding assets on behalf of clients and providing related administrative services. These services are particularly important for institutional investors who require secure and reliable custody of their holdings. Banks charge fees for these services, which can be substantial, especially for large portfolios of assets.
Finally, it’s crucial to understand the macroeconomic factors influencing bank profitability. Interest rate policies set by central banks, such as the Federal Reserve in the United States, directly impact banks' net interest margins. A rising interest rate environment can benefit banks as they can charge higher interest rates on loans, while deposit rates may lag behind. Economic growth and consumer confidence also play a significant role, as they drive demand for loans and other financial services. Regulatory changes, such as increased capital requirements, can impact bank profitability by increasing their operating costs. Geopolitical events and global economic conditions can also influence bank performance through their impact on financial markets and international trade.
In conclusion, banks generate revenue from a diverse range of activities, primarily centered around lending, fees, trading, and asset management. Their profitability depends on their ability to effectively manage risk, adapt to changing market conditions, and provide valuable services to their clients. By understanding the various revenue streams that fuel banks, individuals and businesses can gain a deeper appreciation for the role these institutions play in the global economy and make more informed decisions about their own financial affairs. The complex interplay of these factors demands constant vigilance and adaptation to ensure sustained profitability and long-term stability within the banking sector.